I PASSED MY BOARDS!!!
Waiting for that green check mark and the word “PASSED” to pop up on that screen was stressful but once it did I feel like a huge weight was lifted off my shoulders. With the promise of a paycheck in my future… me and my siblings went out to celebrate!
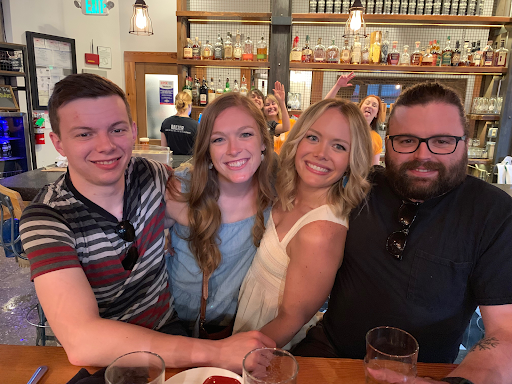
I think it is so important to celebrate your victories. Don’t feel guilty for rewarding yourself when you reach a goal. (Within reason of course).
Now I’m excited to start the next chapter of my life. One thing you should know about me, I’m a planner. If making to-do-lists were a hobby, that would be one of my top 5 favorites. I live and die by my planner. When my planner starts to get to the end and I run out of calendar days, I immediately run to the store to buy another. I know what you are thinking… NERD ALERT. Don’t worry, I embrace it.
So naturally, I had to plan and research what I should be doing while my student loans are in their Grace Period. There is so much information out there and a million different people will tell you a million different things to do. Instead of getting overwhelmed I decided to just break it down into bite size sections. Everything is easier when you go one step at a time!
Plus you know the truly amazing thing about this? Although I may be getting different advice from different people, they all lead me in the same direction! It will all get me closer to financial freedom! It’s easy to get caught up in countless articles about saving for retirement vs paying off student loans or contributing to an emergency fund over paying high interest debt and etc. But when you really step back and look at it there are no detrimental options.
Is it bad to contribute to an emergency fund?
Nope!
Is it bad to pay high interest debt?
Of course not!
The arguments are about optimization and being efficient with your money. What order you choose comes down to risk tolerance and your own personal goals. No matter which order you choose you’re still on the right path! So don’t let information overload stifle your progress or paralyze you.
The planning and research is already going to pay off for me! I learned how to save $3,512.30 in interest and pay off one of my loans 46 months early! All before my payments are due!
That being said here are the steps that I am taking. So take a deep breathe, grab a beer, focus on one step at a time and remember that with every step we are that much closer to reaching our goal!
1. Get Organized
You know that feeling when you just finished all of your laundry? Everything is put away in your closets and drawers and you know exactly where everything is. You mentally plan your outfits for the week. Girrrll I be looking realll cute this week.
Isn’t that such a liberating feeling?
Or on the flip side when its month 2 and you still haven’t done laundry. Everything you own is in the dirty clothes hamper or wadded up somewhere on what used to be your floor. Now it’s just a sea of wrinkled clothes and random socks. You know it’s time to do laundry because you’re out of underwear and you’ve already tried the inside out trick twice. Now try to plan out your outfits for the week.
It sucks right!
That’s exactly how your student loans can be. I have 7 different student loans. Many with different providers, due dates, interest rates, and minimum payments. It’s just a sea of dirty student loans!
List Your Loans
First things first, organize your student loans! List out all of your loans and include all of the important information.
- Provider
- Balance
- Interest Rate
- Term
- Minimum Payment
- Due Date
I just use an excel sheet for this but you can get as high or low tech as you want on this. This simple step gave me such a peace of mind. I know exactly what I have and where. Love that freshly done with laundry feeling!
Extra Bonus: SET UP AUTO PAYMENTS
I have to pay the minimums anyways. Why risk missing a payment. Some loan providers even give a slight discount on the Annual Percentage Rate if you set up automatic payments. If you can’t figure out how to set up automatic payments online just give your provider a call. They will help set it up. It’s almost like they want to make sure they get paid or something.
Loan Forgiveness
Free money!
Apparently this really is a thing. If you have certain loans than you can apply to qualify for loan forgiveness. This is where the government will pay off a portion of your loans after a set amount of time. From what I’ve read it mostly applies to people working in the public sector in low income areas. Most of these programs only apply after you’ve made payments for 10 years.
Unfortunately I do not qualify for any of these programs. But it is absolutely worth looking into. I saw one that repays up to $120,000! SO maybe just check to be safe. To see if you qualify now or may in the future here are a couple of really informative sites I found.
Geared towards physical therapy occupations:
https://www.studentloanplanner.com/student-loan-forgiveness-physical-therapy/
For everyone else:
https://www.nerdwallet.com/blog/loans/student-loans/student-loan-forgiveness/
Subsidized Vs. Unsubsidized
Who cares? Ammi riiiight? Come on Becca this is booorrring!
I know, I know, but knowing the difference between these two will save me thousands of dollars over the life of my loans.
Subsidized Loans
These are the good guys! The government pays the interest for direct subsidized loans while you are in college or while the loan is in deferment. Thanks government! And taxpayers! Don’t worry we’ll pay you back. Literally. Once the subsidized loans go into repayment THEN you start paying the interest on the loans.
Unsubsidized Loans
Booo! These are the other guys. Interest begins accruing for direct unsubsidized loans as soon as the loan is taken out. I have a direct unsubsidized loan through Wells Fargo. I took out $10,000 and the first payment isn’t due until 12/21/2019. But because it is an unsubsidized loan it has already accrued $2,957 and growing.
Why is this important? I have to do it. I’m leaving you on a cliffhanger! I’ll give you a hint, the answer is in Step 3.
Budget
I think I just died a little bit typing that. Budget. Such a gross word. Don’t tell me what to do!
But here’s the thing. It doesn’t have to be a negative word. Instead of looking at it as something telling me what I can’t spend money on I view it as something telling me what I CAN spend money on. GUILT FREE. A good budget is a planner’s wet dream. With a well built budget I know exactly what I am making and spending every month. It lets me see how much extra I can pay in student loans or spend on beer and still be in the clear!
This is a HUGE topic with tons of techniques and tools to help create that perfect budget. However I am not going to get into it on this post because of my current situation.
In case you haven’t heard, I just graduated. To be financially smart I am living at my parents house in Chicago right now while picking up shifts as an Athletic Trainer. I have accepted a job in Austin, TX and I start at the end of August. With so many unknowns I can’t really create a detailed budget. Take home pay, rent, utilities, living expenses, heck if I know!
Don’t worry my budget is coming! Just a little later on. However the concept of creating a budget is pretty basic. Here is a good resource for getting started from scratch.
https://www.nerdwallet.com/blog/finance/how-to-build-a-budget/
There are also a ton of budget apps out there. Mint, YNAB, Clarity, NerdWallet.
The main thing to take away from this is to know your income and know your expenses. This will help in the next step.
2. Get Prepared
Life can be unpredictable. For example growing up in Chicago I never expected that one day I would l live in Austin, have a boyfriend in Colorado, and a sister in Dallas. But that’s what makes life fun! The surprise and the mystery of what will happen next.
What is not fun is when something unexpected happens to my finances. That’s why my top priority even above paying off student loans is having an emergency fund.
Emergency Fund
An emergency fund is just a savings account for a rainy day. The idea is if something unexpected happens, I will be able to dip into my emergency fund to cover it. No I’m not talking about when Taylor Swift concert tickets go on sale or when Sam’s Club has a BOGO on pizza rolls. We all have those friends. But if my car breaks down or I have a medical expense hopefully I have enough in my emergency fund to pay for it.
This is where the arguments online start kicking in. How much should I have? Should I pay off loans first? Where should I put it?
I’ve heard an emergency fund should have anywhere from 3 months worth of expenses up to a full year of expenses. Here is where my risk tolerance comes in to play. How much risk am I comfortable with. At what point do I stop worrying if I have enough.
Dave Ramsey suggests that when you are in debt you should set aside $1,000 for an emergency fund. Good ole Dave. He says $1,000 because anything on top of that should be used to pay down debt.
Again, there is no wrong answer here. Anything is better than nothing.
My emergency fund goal is $5,000. Enough to keep me afloat with bills, rent and eating. I really don’t want to go back to stealing jelly packets to survive…
I am currently at $3,200 but have a lot of new things to purchase as I make the official move to my new home in TX.
An emergency fund is a higher priority because I would rather be prepared for the present than save a few bucks in the future. It reduces stress because I know that whatever happens I will be able to handle it for a certain amount of time. It is like buying a peace of mind!
Moving Fund
My next top financial priority is my Moving Fund. My emergency fund is for unexpected expenses. I have known I am moving for a few months now so I have been able to prepare in advance so I don’t dip into my emergency fund.
My moving fund goal is $2,200.
I am currently at $1,100. And man did that money go fast. So far all I have to prove for it is 2 nightstands, a dresser, and a chest of drawers. How exciting… I don’t even have a bed yet. That reminds me to add that to my to-do-list!
To reach goal I set aside the money in my budget and set up automatic deposits. Set it and forget it! If I see $100 extra dollars in my checking account I might be tempted to spend it. How do you say no to a new pair of shoes? But if I see $100 in an account labeled Moving Fund I won’t touch it.
I have my emergency fund in a high yield online savings account. Two great ones are Sofi (https://www.sofi.com/share/money/2640150/) and Discover. They’re both completely free, no fees, and currently have 2% Annual Percentage Yield which is way better than the current market average.
*** The Sofi link is an affiliate link. If you sign up and fund your account with $100 or more we BOTH get $50 for as long as their promotion lasts! You get $50, I get $50!***
3. Get Paying
Congratulations! You’ve made it to the good part! This is where the big money is saved. This is how I saved $3,512.30 in interest and 46 months on one of my loans! The secret? PAY EARLY. But Becca, my loans aren’t due for 6 months. I know! Isn’t it great? We get a chance to pay off interest and reduce our overall balance before they are even due. There are a lot of reasons to pay early but first a quick recap.
I’ve organized all of my loans. I don’t qualify for student loan forgiveness. I know which loans are subsidized and which aren’t. I know my budget. I have an emergency fund. I have my moving fund.
Yes I am $121,000 in student loan debt but all things considered I feel like I am in a great place. I am primed to start paying off my loans. So why pay early when I don’t have to?
Interest Capitalization
Do I sound smart yet? Here’s a definition from someone smarter than me. Interest Capitalization is the addition of unpaid interest to the principal balance of your loan.
https://www.nelnet.com/interest-capitalization
Since unsubsidized loans accrue interest while in school the interest capitalizes. The Wells Fargo loan I mentioned earlier will have capitalized interest. Essentially I will be paying interest on my interest. That $2,957 of interest will be added to the principal balance at the end of my Grace Period. Sucks right?
This is why it is important to know which loans are subsidized and which aren’t. Federal direct subsidized loans have no capitalized interest on student loans when you graduate because the government was paying the interest while in school.
Lifestyle Creep
Lifestyle Creep (or lifestyle inflation) refers to increasing your standard of living when your income increases.
It’s natural to want to spend more when we make more but I do not want to fall into that seductive trap during my student loan Grace Period. By paying early I will get used to my new financial situation and not get accustomed to a higher standard of living than I can really afford.
Whether you’re paying your loans early or sending that money to an emergency fund don’t let your lifestyle creep up and derail your goals!
Targeting Loans
This is where it all comes together baby! The goal is to knock out the highest interest rates first. Typically any credit card debt would have the highest rates. Luckily I don’t have any credit card debt. Just 6 figures worth of student loan debt.
There are two things that I am looking for when I pick my first target. Highest interest rate and Unsubsidized. Paying off those first will save me the most money because those are the loans that generate the most interest.
This is where the list of loans and identifying Subsidized vs Unsubsidized comes in. Woo was it worth the cliff hanger?
Looking over my list of loans my Wells Fargo loan has the highest interest rate at 7.99%. It is also an unsubsidized loan that is threatening to capitalize the interest!
#targetaquired
Now queue the budget! Hey budget, how much can I afford to pay towards my Wells Fargo loan?
Currently I am saving for my emergency and moving fund but when I reach goal in September I can start by paying an additional $800. Then from October – December I plan on paying $1,000 a month. Here’s where I nerd out. Get ready to get pumped!
Calculate The Savings
I found this calculator online that calculates how much you can save if you pay during the Grace Period.
http://www.youcandealwithit.com/parents/tools-and-calculators/calculators/grace-period-calculator.shtml
Enter the amount of the loan, interest rate, and how much you can pay for each of the 6 months of the Grace Period and hit calculate.
I will be saving $3,512.30 in interest and reducing my pay period by 46 months. How cool is that! How much are y’all going to save? Let me know in the comments section!
Do you hear that? I think the dryer timer just went off. Looks like my laundry is done…
-B

